Industrial & MRO SupplyTX-81AA
Copper Averages $6.59/lb in October, Up 36% Year Over Year
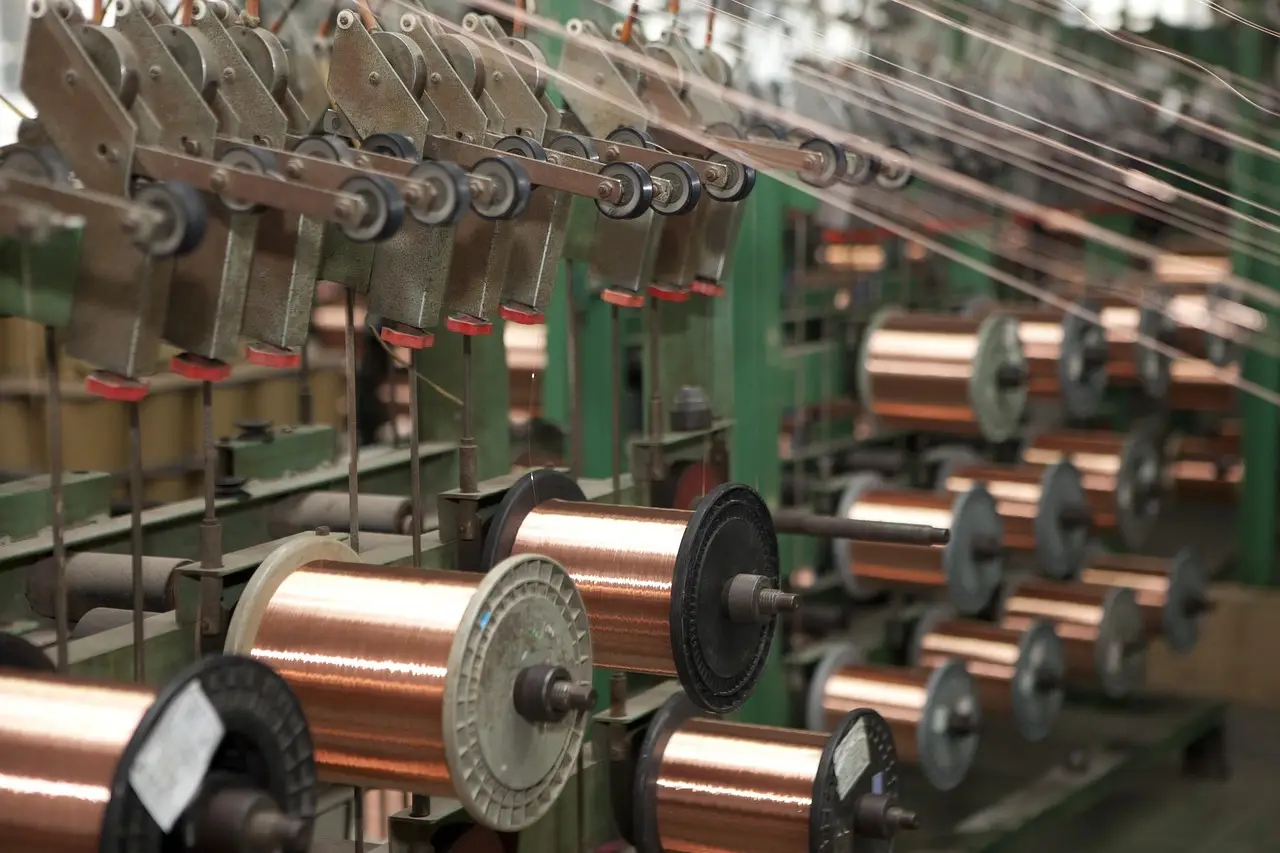
Copper averaged $6.59/lb on the LME in October, up nearly 36% year over year, as Border States reports steel hikes of 5-10% and PVC lead times stretching to 12 weeks.
- Scan date
- November 13, 2026
- Handle time
- 4 min
- Ticket
- TX-81AA
Packing list
Copper's October LME monthly average was about $14,532 per metric ton ($6.59/lb), up nearly 36% year over year
Suppliers implemented 5% to 10% steel price increases at the start of November 2026
Three-inch and larger PVC pipe faces 8-12 week lead times on hyperscale demand
China's aluminum exports rose 16% in the first eight months of 2026
The Fed held rates at 3.75%-4% in a 10-2 vote, with its next meeting December 8-9
Copper averaged approximately $14,532 per metric ton, or $6.59 per pound, on the London Metal Exchange (LME, the global metals pricing benchmark) in October — up nearly 36% from the same month a year earlier, according to Border States' commodity update published November 9, 2026, from Fargo, N.D.
The October average came as the market cooled slightly from September's record highs, a month that saw two separate price increases on copper wire. Suppliers implemented one further copper price increase in October. LME warehouse inventories also rose during the month, though global supply availability and regional inventory differences remain factors to watch.
The year-to-date picture is stark: copper has averaged $6.15 per pound across 2026, against $4.51 per pound in 2025. Average weekly prices from August through October ranged from a high of $6.70 per pound to a low of $6.52 per pound. On the morning of the report, copper opened at $6.25 on COMEX (the U.S. futures exchange).
Supply-side pressure is real. A major miner's Chilean copper production fell to its lowest third-quarter level in nearly two decades after extreme winter weather disrupted operations. Border States notes copper remains sensitive to global supply conditions, mine disruptions and demand from hyperscale projects — the massive data-center constructions now pulling large volumes of electrical materials through distribution channels.
What does this change for aluminum buyers?
Gulf producers are still restoring damaged facilities and building alternative export routes that bypass the Strait of Hormuz amid ongoing Middle East conflict. Chinese smelters, meanwhile, have raised output despite higher energy costs: China's aluminum exports rose 16% in the first eight months of 2026, offsetting conflict-driven supply disruptions.
Indonesia is adding structural capacity. Its aluminum production is projected to grow from 619,000 tons in 2025 to four million tons in 2030, with alumina (the refined oxide feedstock for aluminum) output more than doubling to 9.1 million tons. Analysts cited in the update expect global aluminum supplies could move into surplus in 2027 as Middle East output recovers and Indonesian capacity ramps. Aluminum opened at $2.50 per pound on the morning of the report.
Steel suppliers push 5% to 10% increases
November opened with suppliers implementing price increases of 5% to 10% across steel categories. Demand from hyperscale projects continues to strain manufacturing capacity, keeping backlogs elevated and lead times extended — Border States flags early planning as essential for large projects, particularly those requiring larger-diameter conduit.
Domestic mill results back the pricing strength. Cleveland-Cliffs and Steel Dynamics both reported strong third-quarter profits, supported by lower import levels, steady demand and tight availability in the U.S. steel market.
Trade policy remains unresolved. U.S.-Mexico talks over reductions to Section 232 tariffs (the national-security steel and aluminum levies, currently 50%) reached an impasse. The proposed agreement covered reductions to automobile, steel and aluminum tariffs, but new rates for steel and aluminum had not been determined.
PVC pipe lead times stretch to 12 weeks
Suppliers announced PVC price increases at the start of November, citing higher resin costs and continued hyperscale demand. Resin costs remain elevated, driven by feedstock costs, transportation expenses and construction-related demand.
The lead-time split is sharp:
- Two-inch diameter and smaller pipe: two to four weeks
- Three-inch and larger: eight to 12 weeks
Hyperscale demand continues to drive significant PVC conduit and pipe volumes, supporting both pricing and extended lead times on larger-diameter product.
Fed holds rates at 3.75%-4%
The Federal Reserve voted 10-2 to hold interest rates steady, keeping the benchmark federal funds range between 3.75% and 4% after raising rates in September. The Fed's final meeting of the year is scheduled for December 8-9.
Border States directs readers to its 2026 State of Commodities report for deeper analysis of copper, aluminum, steel and PVC dynamics and the factors to watch in 2027 — with the acknowledgment that no one can predict commodities exactly, but understanding the drivers can help plan the year ahead. For distributors, the practical takeaway is that copper's 36% year-over-year gain, steel's fresh 5-10% increases and double-digit PVC lead times will keep pressuring gross margins and inventory turns into the first quarter unless spot prices break lower.
via tedmag.com (Source)
More from Tom Whitfield
Show full bio
Staff writer covering companies, deals and strategy in Wholesale and distribution industry coverage for B2B professionals at Distribution Brief.
160 articles